
Podcast: Play in new window
Jack Gamble of @NobodySpecialFinance joins David McAlvany to follow the money behind the AI boom. Jack examines the circular financing connecting Nvidia, CoreWeave, OpenAI, Microsoft, and others, along with massive data center spending, GPU depreciation, mounting debt, and the constant need for new capital. AI may prove transformative, but does that mean today’s investments will prove profitable? Jack and David explore the financial risks beneath the AI boom.
“AI is inflationary at this point in time, highly inflationary. And what Secretary Bessent is doing in suppressing yield, that is delaying the inevitable comeuppance that would kill this bubble. All these things we’re doing to keep interest rates from rising, as they naturally need and must be allowed to do in order to restore a healthy economy, artificially suppressing that is prolonging this bubble, which is making the inevitable result of it that much worse.” —Jack Gamble
* * *
Kevin: Welcome to the McAlvany Weekly Commentary.
Dave, today’s an unusual day because we’re interviewing somebody who calls himself nobody special. And when I heard that, I thought, well, then why are we entering into a conversation with nobody special? But I’ll tell you what, this guy is special, isn’t he?
David: Well, you follow the truth where it takes you. And sometimes for us, that’s into economic tomes and things that nobody reads or hasn’t read for 20 years, but should have some familiarity with. That could be economic theories or conceptions which have been left behind, whether it’s the efficient market hypothesis or—
We look at things critically. When I came across Jack Gamble and the Nobody Special podcast, I thought, he’s doing good work and he’s got the mental chops to go deep, partially because he’s trained his mind to do so. When you spend a couple years in nuclear engineering as a mechanical engineer, you start asking questions and you have to find the answer. And like a dog on the hunt, once he’s discovered something, he goes deep, and I appreciate that. So I wanted to bring him into the conversation for the McAlvany Weekly Commentary.
Kevin: One of the things that I enjoyed when I first came to work here was the ideology of your dad. When your dad would see something that other people needed to know, he was on it, and he just made sure that other people knew. And Jack is like that. Jack is driven, even if it’s at a risk to himself, he’s driven to get good information to the people. And what he’s seeing right now needs to be explained.
David: Yeah, the AI bubble has some complexity to it and that’s what we’re going to dig into today.
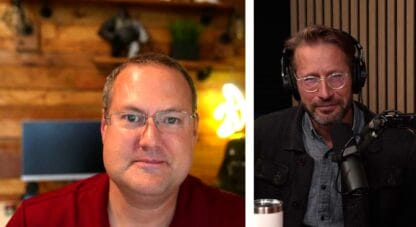
Jack Gamble, great to have you on. Host of the Nobody Special podcast. Mechanical engineer, curious, critical in your appraisal of Wall Street and structured finance. You bring that to your audience on a daily basis. And we’re interested in the sleuthing that you’ve done on AI, what without a doubt is the greatest equity bubble of all time. Today we want to explore accounting gimmickry. We want to explore vendor financing, round tripping of revenue.
Let’s start with some context. The everything bubble ended in the fourth quarter of 2021. Maybe we can dive in on the AI narrative taking root in 2022, perhaps even the backstory, the DeepMind paper from 2027, just to set the context for what this bubble is, how it’s been building, and how it’s, I guess you could say degrading as time progresses.
Jack: Yeah, that’s a really good intro, and it’s the perfect place to start with the AI bubble or the AI mania, as I call it, that Google DeepMind paper, it was called “Attention is All You Need.” That came out in 2017. And that’s where the large language model was basically invented, in that white paper, or the transformer they called it. It was a mathematical model for predicting the importance of a word in a string of text. And when they fed this thing a certain amount of data and it came back with the outputs, they realized this is almost like talking to a person. Almost. It wasn’t quite as good. And so the theory was, if we scale this, if we give it more data and more computing power, maybe we can make this as smart as a person. And then, as you mentioned, the end of the everything bubble, right?
We all lived through the vid in 2020 and then we go through this period of easy money, the stimi cash gets flowing, and then that comes to an abrupt end. At the end of 2021, they announced that the Fed is going to start tapering their purchases, tapering their QE, and then tightening is right around the corner.
It very predictably led to a bear market in tech especially in 2022. And so the tech industry needed that shiny new thing. The crypto thing was played out, the internet of things was played out, Web3 was played out. They needed something to get that hype train going again.
The world was still awash with trillions of dollars in excess capital. The reverse repo was full at the time. And so there was money ready to go to work. And it really looks like in late 2022, they launched ChatGPT, much to the surprise of the board of directors at OpenAI, who found out after Sam Altman had launched the product.
It looks like they fired off this experiment to take the Google white paper and give it all the information they could steal, and finance this experiment with all the compute they could possibly give it, financed by what I now believe is the biggest accounting fraud in human history, the AI bubble. And we’re now four years into that. And as we’ll get into over the next few minutes, we are yet to produce a single penny of profit, and there are yet to be any observable gains in productivity despite increasingly ridiculous science fiction derivative hype talking points from the people who are pushing this experiment.
David: We’ve had CapEx booms in the past, and maybe the most recent was the tech bubble. You could certainly go back in time and look at the building out of the railroads. And without a doubt, the notion that these were revolutionary proved to be true. So it’s not a concern, I think on my part or your part, that AI is here to stay or it has transformative impact to the markets and to how we do life in the future. But it’s a question of how you finance it and what is involved. I think about rails, they don’t really go out of style and they have a pretty decent shelf life. You build them and they’re there for a hundred years or more. In this case, you’re talking about GPU life cycles that don’t really have a hundred-year stretch ahead of them. So this massive CapEx spend, maybe you can talk a little bit about the shortsightedness of what we’re spending and what we actually get for it.
Jack: And those are two great comparisons, the railroad bubble and the telecom, the dot.com bubble, because in both of those instances, you did have a very revolutionary new technology that was very useful. All the companies that borrowed too much and spent too much to develop excess capacity that wasn’t needed went bankrupt, but eventually that capacity was utilized. It was sold for pennies on the dollars when the debt went bad, the empty tracks, the dark fiber, it became known as all the cable that they laid in the telecom. Eventually the market grew into that, and so it produced value over time. That’s not going to happen with the AI bubble. This equipment that we’re building, these data centers that we’re building, has a very short useful life and an incredibly short obsolescence cycle. My friend Ed Zitron and even Michael Burry of Big Short fame have both drawn a lot of attention to the depreciation bomb that is about to go off in the AI space.
Today’s CapEx is tomorrow’s depreciation. A lot of that depreciation hasn’t even started yet. There’s an accounting gimmick called construction in progress where, as long as the data center hasn’t been switched on yet, it’s still being built, and therefore we don’t have to start depreciating the asset. And you’ve got more data centers in construction and progress right now than you actually have operating.
And so, much of the CapEx that has already been spent on GPUs that are still sitting in warehouses because it’s meant for data centers that haven’t been built yet, that depreciation clock hasn’t even started. And then once you do throw the switch, it’s debatable how long these GPUs are going to last. Some say three years, some go as long as seven to 10. It won’t matter because, besides the fact that these GPUs and these data centers are going to depreciate dramatically once you turn them on, and besides the fact that, yeah, AI is not going away—the market will use AI like it used the train, like it used the dot-coms, but it won’t be using data centers.
AI usage, in particular inference, which is the use of an AI model after it’s trained, that’s going to go local. We’ll still be using the big data centers for training the frontier models. You need the most current equipment, big cluster of it to create the model in the first place. That’s training. But training is only 10 to 30% of the demand for these compute clusters at data centers. Most of the demand, some estimates vary from 70 to 90%. Most of it is inference, the actual use of the product after it’s created. And inference is increasingly going local, especially after the token maxing phenomenon we saw at the beginning of this year when a lot of tech companies were telling employees “use it as much as possible.” And then OpenAI and Anthropic switch over to token-based billing because they were trying to clean up their books before their IPOs.
And these companies got their bills for the tokens, and said, “Whoa, everybody stop. Stop token maxing.” And Anthropic and OpenAI were like, “Look at our revenue growth,” never mind the fact that it’s about to plateau because everybody stopped token maxing. And now people are starting to be more choosy about how they use these tokens. You’ve also got pricing pressure from Chinese knockoffs are starting to suppress the price of these tokens, making them cheaper, driving these companies further into the red. And you’ve also got, people have figured out that you can run these things on local hardware.
You can take a distilled model that is 85 to 90% as good as the frontier products, and you can run it on a Mac mini in your house, a Mac mini that might cost you 800 or $900, and you never have to go to a data center for anything, not a single token. It runs locally. And even better, all your data, all your intellectual property, everything is staying where you control it. It’s not going out to the cloud where it can be used to train a chatbot to replace you someday.
And so, I think certainly for most consumer applications, for any business application where data security is important, which is a lot of them, certainly healthcare, legal, I think the future of AI is on local equipment, not cloud, which means these data centers that are being built will be useless in a couple of years, probably sooner.
David: Well, Jack, I’m just picturing Kevin Costner and the Field of Dreams and this notion that if you build it, they will come. And we’ve got Louisiana, Kentucky, Virginia, so many states that are doing just that. Massive deals, massive tax savings, communities are tripping over themselves to offer incentives to build something that they assume will be transformative. If you build it, they will come. So you’ve hit on one particular weakness.
There’s this other issue of, in the early phase of a bubble you get equity investors on board, and in the early stages maybe you’ve got reasonable value on the table. But as the equity of particular companies increases, now all of a sudden you’re paying a lot for a little. You’re not paying a little for a lot, you’re paying a lot for a little. Then in the later stages you’ve got debt and the need for financing even more growth.
The GPU life cycle is one issue which is sort of a critical risk. Talk to us about debt and how these companies are utilizing debt, and maybe some of the implied or the future tense weakness of that structure.
Jack: Yeah. So this is very important for people to realize, because something changed in just the last few months. The hyperscalers, which are your Mag Seven companies, your big guys, your Googles, Microsoft, Amazon, Oracle, their free cash flow has gone negative, almost all of them. Only Microsoft still has significant positive free cash flow, which means their money in the bank is going down. So they can no longer finance this build-out with their other businesses. Microsoft is the only one that makes enough money off of Windows and Office to be able to finance building more data centers. All the rest of them are having to take out debt. And of course, that debt is expensive as interest rates are rising. Everybody’s in the press today talking about rising interest rates.
And so they’re now turning to private credit. Private credit is an industry that has spent the last nine months telling its investors, no, you can’t have your money back, because the assets on their books are not worth what they tell people they are. And so now these private credit companies are being loaded up with data center debt. And Microsoft and Meta and Amazon are not reporting this debt that they’re taking out on their books. They’re using what’s called special purpose vehicles, which anybody who’s around for Enron knows a lot about special purpose vehicles.
It’s when you create a shell of a company for a single project that you’re working on, and then that asset and the debt that pays for it lives on that shell company’s balance sheet, not yours. And so you don’t report it to your investors. You go look at Meta’s balance sheet, you can’t see all the debt they’re borrowing to build that giant data center in Louisiana that they partnered with Blue Owl to build, which Blue Owl is the poster child for the blow-up in private credit these days. And so these private credit facilities are now being used to pay for it.
NVIDIA came out just about a month ago now, I guess, with what I consider one of the most grotesque displays of moral hazard I’ve ever seen, when Jensen Huang and the private credit executives sat around the table at CNBC and congratulated themselves on how they were going to continue to finance this experiment with people’s pensions, IRAs, and 401Ks. This debt is being parked into highly complex, very difficult to see through financial instruments, asset backed securities, and it’s being sold to bond funds. And it’s being aided by the fact that in a lot of cases, NVIDIA themselves is backstopping this debt, providing credit guarantees.
And so, even though these companies are all destined to lose money on these investments, again, they’re yet to produce their first penny of profit, and they’re all deeply indebted, they’re being given investment grade credit ratings by the rating agencies because NVIDIA’s attached. They’re using NVIDIA’s name as a credit wrapper to make these projects look less risky. Again, it’s all being sold to people’s retirement accounts. I think most people are in something like a 60/40 portfolio in their IRA or their 401K. Their guy probably told them it’s nice and diversified, 60% stocks, 40% bonds. That 60% stocks is now almost entirely tied to the AI bubble.
The Mag Seven companies alone are 35% of the S&P 500 now, and that’s just the Mag Seven. You’ve also got utility stocks, Caterpillar, John Deere, GE Vernova, Eaton, 3M, Corning. All of these companies are now trading like AI companies. I mean, John Deere, their biggest growth sector is selling generators to data centers right now. Since when is John Deere an AI company? That is how big this bubble has gotten. It’s now swallowing up everything.
So the 60 in your 60/40 portfolio is already entirely dependent on these AI stocks, whether you realize it or not. But now they’re coming for the 40. Now they’re coming for the bonds, and they’re using private credit to do it. They’re getting investment ratings so they can sell it to these bond funds that are in people’s retirement accounts.
I don’t think the risk on them is being adequately measured and reported to people. And so people who think they’re diversified because they trust their guy to spread them out don’t realize it is one crowded-as-hell trade and everybody is now in it. Anybody with a retirement account is now in this trade.
David: Well, the concentration risk is pretty interesting. Particularly you look at it from a historical perspective, past CapEx booms have exhibited the same thing. 40% of market cap is usually the peak. There’s only one exception to that. And you have to go back to the railroads where frankly there weren’t that many companies listed in the mid to late 1800s. So it got as high as 60% in terms of the rails concentration.
But you look at more recent CapEx booms, and 40% as an expression of stock market capitalization, that kind of concentration is its own version of danger. And so you talked about 35% just in the Mag Seven, and then you expanded that list to other names which are participating on an ancillary basis. And we’re already there at the 40% and probably not going to see 60. But it is an indication, it is a signal that you’re at the end of a cycle, not at the beginning when you begin to see that concentration.
What do you think about Trump’s executive order allowing for alternative investments into 401ks? You talk about the 60/40 mix and investors not knowing that they’re participating because they’re not necessarily going out and buying Nvidia. They’re not necessarily going out and buying Taiwan semiconductors or SK Hynix, but it’s there and it’s on a permission granted basis. How do you think that ages?
Jack: It’s going to age very poorly. I think President Trump is going to regret how much he’s attached his political self to this bubble, especially with the Stargate announcement, that big data center project he’s doing in Texas.
On the alternative assets, I mean, I’m generally a small government guy. I’m generally in favor of less involvement of the government in telling me what I am and I’m not allowed to invest in my retirement account. That being said, what’s going on with alternative assets, private equity, private credit, crypto is not democratization. It’s not giving the little guy the same opportunity as the big guy. That’s the line they’re feeding people, and it’s BS. What it is is they’re looking for bag holders. Private equity took all the easy money in COVID, and they way overpaid for assets—assets that they cannot take public at what they paid for, they can’t sell, and their investors want their money back.
And most of the returns in private equity space in the last few years have been things like pick interest payment in kind, where instead of actually paying back the loans or the debt they took out, they just make the principle bigger. They’ve been using net asset value financing, continuation vehicles, continuation vehicles of continuation vehicles where they create new funds, put the holdings from the old fund into the new fund, take the investors in the new fund’s money, use it to pay back the old fund investors. If that sounds like a Ponzi scheme, that’s because it’s almost exactly what a Ponzi scheme is.
These companies are desperate for money to be able to return to their investors, but they can’t find anybody to pay the price they advertise for these assets. And so along comes President Trump, makes it clear you can go ahead and dump these assets into people’s retirement accounts.
And we’re all getting a firsthand look at what that looks like right now with this fiasco with Mark Walters involving the LA Lakers and the Dodgers and his insurance companies because what they’re doing with 401ks and IRAs, they’re also doing with life insurance. They’re taking assets that they can’t sell to anybody else and they’re using their insurance balance sheets, their clients’ money as liquidity. And I do think Trump’s going to regret that.
David: It’s not as if private equity and private credit are a bad idea. You just have to know where you’re at in the cycle. When Swensen at Yale running the endowment 30 years ago is looking at private equity and private credit as a way to enhance returns, capturing an illiquidity premium makes all the sense in the world. But now we’re 30, 40 years on, and you start running out of new money, and it’s the bag-holder into the cycle. That’s where you got to find new money, and it’s the little guy. The little guy ends up being the liquidity factor for anyone who wants to exit, and coming in late is never a good idea in any market.
That brings us back to the AI bubble. I’d love for you to talk about the round tripping of revenue because the accounting gimmickry and the vendor financing is also one of those things that would suggest we’re late cycle. You’ve got to get more and more creative to keep this thing going, to keep the energy of the bubble where people are interested, titillated, looking at it as the newest shiny object. You talked about the lemonade stand in some of your daily and weekly missives. Great little story that kind of captures the absurdity of what is purely accounting gimmickry. You want to take a stab at that?
Jack: So the lemonade stand analogy I’ve used, it’s been a while since I told this story. See if I can dig this one out of my brain. So a little girl starts a lemonade stand, and she borrows some money from her dad to buy some lemons. Dad gives her some money. She makes 10 glasses of lemonade on her first day. She sells them for a dollar apiece. So she made $10, but dad gave her $20 to start the lemonade stand. So she sold out, but she lost money. So she goes back to dad and says, look at all the money I made. I want to do this again tomorrow. Dad says, okay, let’s scale up this operation. Gives her even more money, gives her $40, buys more lemons, more sugar. She goes out the next day, she sells 20 glasses of lemonade. Dad, I made 20 bucks.
My revenue growth is 100% day over day. Look at the explosive growth. The demand is insane. Dad says that’s great. You’re growing everything. Nevermind the fact you just lost 40 more dollars, but your revenue is growing. And so the sleazy uncle overhears this story, and the sleazy uncle gets involved and says, let’s go to the bank. Let’s take out a loan for $100,000. We’ll backstop it. We’ll borrow against it, citing the revenue growth and the explosive revenue growth. Then we’ll buy all the lemons. We’ll take this thing, we’ll scale it up and we’ll sell derivative instruments based on future glasses of lemonade that could be sold by the daughter.
And as all of this is going on, nobody is advertising the fact that dad and the sleazy uncle are the only people buying the lemonade this whole time. They’ve actually bought all the glasses. So there’s no actual organic demand. It’s been created by dad and the sleazy uncle. The financing has been created by dad and the sleazy uncle, and the bank is holding the bag on this whole thing. And in this case, you’re the bank, you’re the retirement.
It’s very important to see where the rubber meets the road, how that story is reality. Anthropic and OpenAI lose money, and they lose money hand over fist. In 2025, Anthropic lost $42 billion on nine billion in revenue. For every dollar that comes in, four go out. Or you should say five go out, they lose four. OpenAI, same thing. They lost 38 billion on 13 billion in revenue. These companies are not profitable. They’re not even close, and they’re not getting better. They talk all in the press about the revenue. They invented the statistic ARR, annual run rate, where they take their best week or their best month and they multiply it by 12 and they say, look what our revenue is now, but they’ve never actually produced a year of revenue at that rate before.
And they never talk about how much money they’re losing. How much they’re raising, sure. How much they’re bringing in, sure. But they never talk about their losses, and their losses are huge. And OpenAI and Anthropic are holding up the whole bag. Now, the guys who are selling the hardware are making a ton of money. The guys who are buying the hardware and creating the data centers using the hardware Nvidia and AMD sold, they’re doing okay, but you can’t really tell because they have gigantic other businesses, that it’s really hard to sort. What is Microsoft Windows making and what is stupid Copilot they forced into the spreadsheet app? What is that making? Then you’ve got the NeoClouds, which is a whole new industry that was just invented by Nvidia and Wall Street really for the sole purpose of inflating Nvidia’s revenue. And then at the very bottom you’ve got the Frontier Labs, Anthropic, and OpenAI holding up the whole thing while losing money.
And the circular financing is where the hardware manufacturers have figured out, I can just give them money. I can give my customers money and they can give it back to me and I can report it as revenue when it comes back. Now, if they don’t do that, there is no demand for their product. And right now we have no idea what the actual organic demand for these products are. And the example, how I got started down this whole rabbit hole was actually almost three years ago now, summer of 2023 when Nvidia kept posting these magnificent revenue beats and out of nowhere comes this company CoreWeave. Nobody had ever heard of them. In August of ’23, Nvidia reported a $2.3 billion data center revenue beat. And that number, somebody on Twitter pointed out, perfectly coincided with a $2.3 billion line of credit that CoreWeave had just taken out to buy Nvidia chips.
So I started looking at this company CoreWeave, and I find out they’re not tech gurus. These guys are financial engineers. They’re hedge fund guys. They were ethereum miners before that. Before that they were carbon credit traders. They ran a network of shell companies in the Cayman Islands that they ran carbon credits through, not outright illegal, but a lot of people who do illegal stuff do exactly that.
So I look into CoreWeave and since I started looking into this, we’ve had Nvidia invest in CoreWeave in some of their pre-IPO capital raises. So Nvidia gives CoreWeave money. CoreWeave gives them money right back to Nvidia to buy Nvidia’s chips. Nvidia rents those chips back from CoreWeave. I kid you not, $6 billion backstop. Nvidia is now renting the chips that they sold to CoreWeave back from CoreWeave. And then Nvidia had to come in and backstop CoreWeave’s IPO to make sure they could get it out the door.
Now CoreWeave lost $110 million three quarters ago. The first quarter of this year they lost $451 million, and the most recent quarter they lost $740 million. CoreWeave is not profitable, and CoreWeave is not getting profitable. They’re getting further away from profit, but they keep buying Nvidia chips and Nvidia keeps giving them money to do it with.
Now we spoke about concentration risk earlier. Who are CoreWeave’s customers besides Nvidia? CoreWeave’s biggest customer is Microsoft, and their second biggest customer is OpenAI. And Microsoft’s biggest customer is also OpenAI. About 70% of Microsoft’s cloud revenue is OpenAI. So who is CoreWeave—who loses money—who are they really renting to? OpenAI, either directly or through Microsoft as a middleman, or to Nvidia themselves? And again, OpenAI loses money. $38 billion lost on 13 billion in revenue. So you’ve got Nvidia is feeding the cycle. At every stage Nvidia is involved in financing, either directly giving the money, backstopping the debt, or renting the product themselves.
And you got Lambda Labs. This one was just announced today. This is the most recent example. And keep in mind, guys, a story like this comes out every day now. There’s another one every single day. I miss them now they’re so frequent. Lambda Labs just announced a $35 billion deal with Anthropic. Anthropic, who Nvidia invested in, rents a data center from Lambda Labs. Lambda Labs, who Nvidia invested in, rents chips directly from Nvidia, or I’m sorry, leases the chips directly to Nvidia. That’s interesting. Nvidia sold chips to Lambda just so they could lease them right back. And of course, Hut 8 is the company that’s building this data center. They sold the chips to Nvidia that Nvidia is leasing from Hut 8 so that they could lease them to Lambda so that Lambda can lease them to Anthropic. Hut 8 takes that lease that they signed with Nvidia and they go to the bank and they borrow money against it, and they’re like, look, this is a lease from Nvidia.
It’s the biggest company in the world. They’re worth $5.5 trillion. Of course, that’s like money in the bank. That’s that credit wrapper, Nvidia using their backstop. So now Hut 8 can get the billions of dollars that they need to build a data center. And where does that billions of dollars go? Right back to Nvidia. Nvidia is involved in every transaction at every step of the supply chain, bankrolling the debt, selling the chips, renting the chips back, renting the chips out to the customers, investing in the customer who’s renting those chips out. Without Nvidia, none of this demand exists. And now Nvidia has done this to the tune of some $500 billion spread out across all the players in this market. Now Nvidia’s backstopping the debt. A lot of people say Nvidia makes money hand over fist. Who cares? It’s solid gold. Well, no, it’s not.
There’s a reason why you don’t keep your fire extinguisher right next to the stove. Maybe your stove has never caught fire before, but if your stove does catch fire, you can’t get to the fire extinguisher because the burning stove prevents you from reaching it. The same failure mode that’s burning your kitchen also incapacitates your fire extinguisher.
And so I use that analogy to describe Nvidia backstopping debt. In any scenario where Nvidia’s backstop would need to be called upon is the same scenario where Nvidia’s sales fall off a cliff, because if OpenAI or Lambda Labs or Anthropic can’t afford to rent these data centers and Nvidia has backstopped the debt against them, that means these companies are no longer buying chips from Nvidia, and Nvidia no longer has the money to pay those backstops. It’s the same failure mode takes down the whole thing. And the thing holding all of it up is Anthropic and OpenAI, who lose tens of billions of dollars. If they can no longer raise more and more capital, this whole thing comes crashing down and it takes everybody with it.
David: I’m curious, you’ve got groups like Amazon, Microsoft, they’ve taken significant positions in OpenAI, Anthropic, and they get to mark on their books, they get to mark, I don’t know if it’s mark to market or mark to make believe, but the new value of their equity stakes, and that improves their numbers on a quarter over quarter basis.
Jack: It doesn’t just improve them, Dave, it doubles them. It doubles them. And what you’re alluding to is an excellent point, earnings quality. The hyperscalers, take four examples, Alphabet, Amazon, Nvidia, and Microsoft, because they’re the four big ones. Well, let’s leave Oracle out for now. Oracle’s even worse. Their combined pre-tax revenue or pre-tax income for Alphabet, Amazon, Nvidia, and Microsoft was 333 billion in this most recent quarter, massive. And you turn on any of the financial news and you’ll hear how robust tech earnings supports the underlying AI economics. That’s one of their favorite talking points, robust tech earnings. 333 billion in combined pre-tax income. Operating income, their actual business making money, was only 173 billion. Now that’s all the money they made on Windows, all the money they made on cloud, Nvidia selling chips. To get to 330 billion in pre-tax income required $160 billion worth of other income.
And other income is gains on their investments in the debt or the stock in their own customers. Most of that was from Anthropic. Like Google classically reported like $60 billion of gains in their investment in Anthropic. Similar things have been done with OpenAI. Nvidia has also done it with CoreWeave. So all of these companies are all investing in the same companies, their own customers, at increasingly higher valuations. And every time they raise the valuation, they go back in their earnings call and they report gains on investment income.
So there’s not really a lot of actual business creating these robust tech earnings. It’s just paper gains on illiquid securities. Now maybe they actually end up turning an investment. Maybe the IPOs in these companies go well and they convince low information people to buy these stocks and they manage to get out before the bubble bursts. But the other thing I would point out is about the operating income itself is also largely sourced with cloud rentals to these companies, to Anthropic and to OpenAI. And so what’s actually behind these robust tech earnings? You’ve got just paper gains on securities or money that they’re making from companies that can’t afford to keep paying them if they don’t find more investors soon.
PART 2 OF 4 ENDS [00:32:04]
David: All right. So two things. One, come back to the drop in earnings based on the depreciation cycle. So that’s one. And then the second thing I’d love for you to come back to is, yeah, the benefit to Silicon Valley from all of this. You look at the VC funding and just the massive amount of money that’s been made in this bubble. And a lot of it was almost like rocket shipped out of the failure of SVB, Silicon Valley Bank. 2023, I think that’s right.
Jack: Yep. March of ’23.
David: Which was essentially a bailout of Silicon Valley players. If you look at the balances that they kept at the bank, well above the $250,000 of insured deposits, you had to take care of Silicon Valley. So anyways, there’s not a clear question there, but I would like for you to come to the earnings impact from depreciation, that cycle hanging over this quality of earnings issue, which as you just noted is actually distinct in and of itself what they’re claiming in terms of the gains. But yeah, start there and then work back to SVB and Silicon Valley VC guys.
Jack: So let’s talk about that scenario you talked about, the depreciation. Let’s say this all happens at once, and it will all happen at once because it’s a common trigger. Let’s say an OpenAI or an Anthropic go under because they lose tens of billions and they can’t find anybody else to bank for all those losses. The depreciation cycle kicks in. All the money they’ve spent on compute, all that CapEx now turns into negative earnings as it depreciates. All right. So future earnings are now impaired by depreciation of yesterday’s CapEx. And this hits all of the Mag seven because it’s in the hundreds of billions. I think it’s expected to break a trillion next year if they go through with it. So you’ve got the depreciation starts to hit their earnings as these GPUs age. You’ve also got markdowns. If this does happen, then all those other incomes that I just mentioned, the paper gains on securities, those turn into negative earnings as they start marking down the value of the stakes that they took out in CoreWeave and OpenAI and Anthropic and all the other players.
So that hits their negative earnings. Their cloud revenue falls off a cliff because most of their cloud revenue is coming from OpenAI and Anthropic. I mean the concentration here, I finally found this section in my note. Anthropic and OpenAI make up 70% of hyperscaler AI revenue. 70%. It’s the same two companies that are losing tens of billions. OpenAI alone is 70% of Microsoft’s Azure revenue. So as the depreciation and the markdowns hit, so does their revenue fall off a cliff. And then, like we were talking about with the fire extinguisher and the stove, this is now the scenario where NVIDIA has to cough up the cash to pay all these debt backstops that they’ve already signed up to, assuming the legal language in these contracts is actually good enough that NVIDIA doesn’t weasel out of making these payments. And if they don’t, well then it’s your IRA and your 401k that are paying directly because that’s where this debt has been parked. And all of these scenarios would be triggered all at the same time with the collapse of either OpenAI or Anthropic.
Now, as far as with Silicon Valley Bank, sorry, that was the root of the question. In March of ’23, this bubble was, I mean on a percentage wise, to back fit that and do the math, let’s say conservatively 5% of what it is today as far as how much CapEx they had invested, how much the market had rallied on AI, how many data centers had been built, how many of these new neocloud companies had popped up, how much the Mag Seven stocks had rallied. I mean, we’re at the point now where it’s like some $20 trillion of market cap in the S&P alone has just ballooned around the AI bubble.
It was much smaller back with Silicon Valley Bank. And maybe if they had let Silicon Valley Bank go under and all those money-losing companies had not had their deposits guaranteed by essentially the taxpayer, the deposit insurance fund, the average person who pays into that, then this bubble would not have continued to inflate in that scenario. But, as always, they socialized the losses and enabled this to continue.
David: There’s a variety of risks. A recent guest on our podcast, Jim Rickards, looked at financial market risk and national security risks in terms of a functional use of AI and the potential downsides. The things that keep him up at night are financial market volatility running out of control as a result of AI models and trading algorithms going off the rails. National security he looks at similarly.
We don’t have a clean system, but you can add to those big picture things, assuming that you’ve got a really highly functioning large language model integration into these spheres. On top of that, you’ve got hallucinations and work slop and things that, frankly, they’re a different kind of risk and have to be addressed before you even get to Rickards’ concerns because you have to have a system that is really working at an optimal level. And it would appear that, again, in terms of the quality of work that the large language models are doing, it’s not necessarily getting better.
We’re not marching, we’re not sprinting towards AGI. In fact, we’re in this phase where you could argue we’re spending more, we’re getting less in terms of quality. So maybe you could talk about those risks, the hallucinations and work slop before we even consider what Rickards would say are the macro risks.
Jack: I mean, generally in my experience, and I do use AI, I use it for research and for collating data. In my experience, they have about a 20% hallucination rate, 20% failure rate. For every 10 things it tells you two are wrong. And I come from nuclear power. That was my background. You mentioned I was a mechanical engineer. I worked in commercial nuclear power for 15 years. A 20% failure rate is intolerable. A 2% failure rate is intolerable. So depending on the risk tolerance of the application, and I can’t think of any scenario where a 20% error rate would not be just catastrophic for any kind of mission-critical work. Certainly in any kind of life critical work, you wouldn’t tolerate anything even remotely close to that. So if you are using these products, my advice to you would be, strongly, take all the time it’s saving you and double check what it’s telling you because I promise you the errors are in there.
And if you actually take the time to double check it, assuming you don’t miss something and cause a big accident, have you really saved that much time? In my experience, it does save a little time, a little, not nearly as much as they advertise, but it can help you find things and then you got to spend a lot of time making sure it’s not wrong.
As far as financial risk and financial instability risk, I’m less concerned about a chatbot making a mistake causing dysfunction in markets. As much as I’m concerned about the demand for capital in the AI bubble is now so extensive that it is competing with the US government for borrowing dollars, driving interest rates higher. I mean, we’re all watching rates move higher right now and a big source of those higher interest rates is the insatiable demand for more capital to keep building these things.
And the most dangerous thing to financial markets is a shortage of liquidity. It wasn’t the virus that caused the Fed to print money in March of 2023. It was the disorderly unwind of the basis trade, right?, when they would sell a US Treasury future and then buy the corresponding Treasury and harvest the arbitrage difference. When that started to unwind in March of ’23, the Fed turned on the money printer like that, instantly. That is what is a real existential threat to the market. And right now AI is making that scenario more likely because it’s gobbling up all the liquidity that the bond market needs. And as far as the national security thing goes, I can’t tell you. I’m so sick and tired of hearing this China thing. If we don’t, China will. Oh, all the people who are opposed to data centers are paid by China. No, they’re not.
I’m opposed to data centers. If China wants to pay me, I won’t stop them, but they’re not paying me to oppose data centers. I’m opposing data centers because they’re stupid and they’re going to cost people their retirements.
The Chinese will spend the next 50 years recovering from the last time they built way too much of something nobody needed, financed by an immense debt bubble, the Chinese real estate bubble. They built entire cities nobody needed. We should not return the favor by doing it ourselves with data centers. And the idea that if we don’t, the Chinese will, it’s not.
And the reason why the Chinese are coming out with DeepSeek and selling them at 1% of the cost in OpenAI and Anthropic we’re selling for is because the Chinese know this bubble now hangs over the United States like a Sword of Damocles. And if they can pop the bubble, they can cause immense financial and geopolitical problems for the United States that strengthens their position.
David: Well, it ties directly into the debt market. So we have Jackson Hole last week and a clear difference of mandates and needs, if you’re looking at the Treasury Department’s need to keep a cap on interest rates. And to the degree that inflation remains sticky, as Warsh said on Friday, “We have more work to be done.” The hawkish commentary at Jackson Hole, it would appear that there’s a disconnect between the two. I’m sure they’re talking, but you want lower rates to keep the bubble going. You want lower rates to keep the S&P inflated. That helps on the job side. But there’s this nasty thing that’s been hanging around for over five years, and that’s an above target inflation rate. 2%, we’re not even close to it. Maybe we’ve gotten closer relative to 2024, 2025, but not enough progress for him to truly be dovish. So he’s speaking hawkish. If he’s actually going to take action, that remains to be seen.
But you’re right, there’s this competition in the debt markets. Investment grade needs lots of capital flowing. That’s in direct competition with what the Treasury needs. We’ll have close to two trillion in new financing needs this year. We have close to 10 trillion in debt that’s rolling over, and it’s not at the legacy 2%, it’s more at the 4% range, double what we have. So the interest component is blowing out, 1.17 trillion already year to date in terms of the interest paid. One in five tax dollars is going to pay interest. It’s not sustainable. It’s right on the edge, and we got to keep everybody who’s sitting in Treasuries as happy Treasury holders. And here we’ve got, again, the shiny object, but why wouldn’t you? Why wouldn’t you take a Treasury position, swap it for an extra 150, 200 basis points of yield, move into investment grade where it’s a layup because NVIDIA’s changing the world.
And so the migration out of Treasuries is not helpful to Treasury and the migration into investment grade, it seems to make a lot of sense if you’re looking at the reward side of the scenario, not balancing out risk and reward. Credit spreads are the tightest we’ve seen in a long time. People are not cognizant of the fact that bonds are really not that much safer than stocks. And if there’s a lesson from 2022, you’re 60/40. As you talked about earlier, the 60/40 can hit you on both sides.
Jack: And remember what killed Silicon Valley Bank besides a run from its depositors was losses on US Treasuries. This perceived safety of bonds, I don’t really subscribe to that to be honest with you. Treasury bills, sure, a one month, a three month. If rates go up, just hold it to maturity. But a 10 year, 20 year, 30 year. What are they paying? 4.8%, 4.78? No, thanks.
In Kevin Warsh’s speech on Friday, he devoted the first three or four minutes besides the stuff about the hikes around Jackson Hole— He talked an awful lot about productivity gains from AI being disinflationary and all that’s on the horizon. Let me tell you, it is four years into this now, and besides that AI is yet to produce its first penny of profit. We also have no observable gains in productivity.
The San Francisco Fed just updated their chart. Total factor productivity since ChatGPT was released in 2022 is up 2.45%. That’s actually slower than the rate of productivity growth before ChatGPT was released. Now I’m not saying ChatGPT has slowed productivity growth, but it certainly has not increased it. There is no observable increase there. And just for context, shortly after Netscape Navigator was released in the three and a half to four years after that was released, total factor productivity grew by 7.5%.
So we did have productivity growth after the dot-com bubble. It wasn’t enough to stop the dot-com bubble from bursting. We have no productivity growth. We have been promised this productivity for years now, some of the silliest promises I’ve ever heard, and it is yet to show up, as has the first profit.
So I think Chairman Warsh is deluding himself about these productivity gains. Now, what we are seeing from the AI bubble is we’re seeing an unnatural demand for memory, for copper, for electricity, for generators, for transformers, for solvents, for any number of things, fiber cable for connectors, all things that the prices are going up on, driving inflation higher. AI is inflationary at this point in time, highly inflationary.
David: Yet.
Jack: And what Secretary Bessent is doing in suppressing yields, you mentioned that a little bit, that is delaying the inevitable comeuppance that would kill this bubble. All these things we’re doing to keep interest rates from rising as they naturally need and must be allowed to do in order to restore a healthy economy, artificially suppressing that is prolonging this bubble, which is making the inevitable result of it that much worse. So I really wish they would just take their fingers off the scale, let the market figure out what is the actual price of money, interest rates, and that alone would be enough to stop all this silly borrowing that’s going on in data centers, but they won’t let it happen.
David: Yeah. You’ve got Warsh’s protege and Bessent’s protege basically saying, “Don’t tinker with the price of money. Don’t tinker with the price of money.” If it takes five and a half percent for the 30-year to clear, if that is the price of money, you’re getting an invoice. It’s not a bond crisis, you’re getting an invoice. This is what the world is determining is the proper price of capital. If you’re going to fight that, you’ve never had that kind of a fight, one. Bond market’s bigger. Bond market’s bigger.
Jack: James Carville, right? If he dies, he wants to be reincarnated as the bond market-
David: As the bond market.
Jack: Because it intimidates everyone. And look, Secretary Bessent strikes me as a very competent, knowledgeable person. I know that the jury’s out on him and there’s political angst around him, but he is toying with forces he can’t possibly control. It doesn’t matter how smart and capable you are. The bond market is the combined knowledge and wisdom of all of humanity acting in unison about the supply and demand of capital. One guy cannot control that, and he’s going to break things if he keeps doing this. And where we should be today, we had Japan and the UK, their 10-year yield is the highest it’s been since the mid-’90s, like ’95, ’96.
We were at 4.78 or so when we started this talk, which is the highest we’ve been since January of last year. If we were not messing with the yield curve with all of the buybacks and all the things the Fed is doing in order to keep the issuance of T-bills higher and the long-end stuff lower, if we were back in the ’90s with our interest rates, we’d be closer to 7% right now on the 10-year like Japan and the UK is. I think that’s where the market wants this thing to be. I mean, I’m not going to sit here and tell you that would be good for anybody. It would be horrible, but it’s probably coming at some point in the next few years.
David: Well, the wheels come off in the bond market if that’s the case. That’s the death of the 40% and higher cost of capital, discounted cash flow models, it’s also the death of the 60.
Jack: Yeah, it’s not fun for anybody.
David: No.
Jack: Neither is continuing on the inflationary path that we’re on, for anybody.
David: All right. So cost of lemonade and who’s buying it. I think it’s lost on most investors that this issue of vendor financing is very real. It’s extraordinarily large, and it’s highly consequential. It’s not sustainable. And the implications are that the AI trade, when it flips, you’re not giving up 10%, you’re not giving up 20%. We go back to the dot-com bubble, your best case scenario is a 50% loss. And in a lot of instances, you’re either looking at bankruptcy or an 80 or 90% loss. And I was a broker in that time frame and I still had people wanting to buy the dip on Sun Microsystems. And they just couldn’t fathom that the best wasn’t yet to come. You look at a company like Intel, how long did it take for them to get back to those all time highs? You talking 15, 20 years. It’s astounding. And people don’t realize that when you overpay for an asset, your future returns, from a mathematical standpoint, are guaranteed to be subpar, maybe even deeply negative.
The benefit of being a value investor is that you’re looking for quality at a great price. That’s not what is operable today. There’s so much FOMO here, you got to get in. You got to get in while you still can. The narrative is so powerful. If you had to pick one thing that was sort of a trend shift in the narrative, what causes people to say, “Wait a minute, hold on a second.” Because it seems like we began to see that even a few weeks ago with debt issuance and the market’s response as they’re looking at funding further CapEx, you get through a quarterly report with one of the hyperscalers, the data centers, the semiconductors, and the more they talk about debt, the more the market says, “No, I don’t know about this.” So have we already seen it? Is debt issuance the issue, or what would be the issue in your mind? Full stop on the narrative.
Jack: So I don’t think we’ve seen it yet, that “this is it” moment, right? Because right now they’re still able to take out that debt. These companies that lose money hand over fist are still able to borrow at investment grade ratings. And so everybody can afford, still, to continue on this trend, and it should worry people. It should worry people immensely that somebody who loses $40 billion in a year is able to borrow hundreds of billions of dollars. I don’t understand why. Well, I know I understand why, because these people don’t get the messaging about the negative free cash flows and the losses. They only get annual run rate. They only get the revenue is crazy. They only get Jensen Wong and his leather jacket saying the demand is insane. By the way, Jensen Wong has twice had to settle with the SEC for accounting fraud, for financial fraud reporting, twice. They never tell us about that. They never mention that on the financial press. So I think that moment still hasn’t been hit. I mean, you could say it was not Lehman, who was it in summer of 2007 was the first indicator.
Kevin: Bear?
Jack: Bear. We haven’t had our Bear Stearns moment yet. And then Bear Stearns was a few months before Lehman even when Lehman was the big blow up. So I don’t think we’ve seen that yet. It’ll be one of these Frontier Labs unable to raise capital that finally kills the bubble officially, like “He’s dead Jim,” at that point.
David: And it probably won’t be— If you go back to the GFC, it was two hedge funds, $400 million. I mean chump change. And you were a good 18 months before it kind of set in and the whole paradigm began to shift. But you had the canary, it was there, the trend began to shift, liquidity began to shift. And then when it became a market reality, liquidity wasn’t there, things moved really fast, but it was technically in motion for 18 months.
Jack: And there’s one other thing I would point out that, at risk of sounding cliche, it’s different this time. And that is passive investing, passive flows. When the dot-com bubble happened, passive wasn’t really a thing, at least not mainstream. There was mutual funds back then, but the average person wasn’t in a SPDR ETF back then. It was just starting to really become a thing when the GFC happened. That was when the Vanguards and the BlackRocks started taking over everything.
So now, with the average person, most of the population in the States, invested heavily in a passive vehicle like that, we don’t know what a sudden sell-off across the board even looks like. So that means there’s going to be a lot of beautiful babies get thrown out with the bathwater, with the AI bathwater, when that happens. A lot of perfectly good companies are going to get sold off, dragged down by the indexes and the passive flows.
And so if you’re lucky enough to come out of that with your head still attached and some capital, there’s going to be some great opportunities there because I think a lot of good companies are going to be very cheap for a stupid reason. But getting to that point with your head still attached will be a challenge, and it’s harder than it sounds.
David: Well, what you’re getting at with the passive flows is that most of that money’s coming into cap-weighted indexes. And so there’s a disproportional share that goes to the winners, which works in the right direction. In the wrong direction, it’s a disproportional flow out of those same shares. And so the drama in those names can be exaggerated just as it was on the upside. So the expectations of investors that this carries forward in a positive fashion, yeah it will. It will as long as there’s liquidity in the market. And then when the liquidity dries up, the dynamic shifts. And I think you’re right, there’s a fresh dynamic which is passive investor flows into cap weighted indexes. They get a double dosage on the downside.
Well, fun to see— Well, fun. I don’t know if that’s the right word for it-
Jack: Doesn’t sound fun.
David: But thank you for looking at these things in depth. What I love is that as an engineer you need to make the math work. Things need to tie out. And so part of what drives your curiosity is embedded in your personality. I love that. But for you to go down the road of looking at CoreWeave and looking at the Capital Group that’s investing in the Caymans in carbon credits, a lot of people would not take the time. But what I love about the Nobody Special podcast is that you’re basically saying “It’s right there. If you want to find it, you can. The reality is you don’t want to know.” Wall Street doesn’t want to know. The mainstream media does not want to know. The average investor does not want to know, but there’s a responsibility factor here. If you just open your eyes, it’s right in front of you. How long did it take you to dig into Magnetar Capital and the shenanigans that they’ve been playing now on going on two decades?
Jack: I got to Magnetar in about two days. I can tell you when I first heard about CoreWeave, I got to the carbon credits in the Cayman Islands in about five minutes. Company website, CEO’s name, LinkedIn page, Google the name in a couple of companies he used to work at. Within five minutes, I’m on the Paradise Papers and the International Consortium of Investigative Journalists looking at this spiderweb network of at least 20 shell companies in the Cayman Islands. And the nomenclature on these companies suggested there could be as many as 60 of these. It’s just this particular leak was of one law firm that people were using to generate shell companies. And shell companies in the Caymans, it’s not illegal to do, but there’s a lot of reasons to do it that are illegal, like money laundering, like transfer mispricing, tax evasion, all kinds of scams involve that.
And that was at least like, whoa, who are these guys that are single-handedly driving Nvidia’s earnings, that is single-handedly propping up the whole stock market after the bear market of 2022? Nobody asked. And then I got to Magnetar because Magnetar was leading almost every investment round. And then Magnetar’s history, I mean, that scene in the Big Short with the Asian guy at the sushi restaurant, that was Wing Chau who worked at Harding Advisors. Harding Advisors was assembling CDOs, and Magnetar Capital was handpicking the bonds to go into those CDOs. And then they would be sold to investors while Magnetar shorted them, bought credit default swabs on them. So the investors who bought those CDOs didn’t know that Magnetar Capital had assembled them and was betting on their failure. And Magnetar, the CDOs that they had assembled had like a 90, 95% failure rate versus the 65% individual market average.
So you’ve got a hedge fund that is notorious for creating sabotaged investments, selling them to unsuspecting investors while betting on their failure, is the financier of this company that’s holding everything up. And these guys used to run shell companies in the Caymans. And I’m just like, “Hey, somebody ask questions about these guys. They’re not going to sit for an interview with me. Somebody ask this question.” And not only— You mentioned the financial press, they don’t want to know. They don’t want anyone to know because there was no coverage of any of this in the press. There was an article that was written by an analyst at Bernstein who put out a research note saying, “Don’t get your investment advice from Twitter randos.” And it was basically, there’s this guy on YouTube, on Twitter, talking about CoreWeave, ignore him, all kinds of personal attacks in the headline, never mentioned me by name so the reader wouldn’t know how to find this work if they read the article.
They just told the reader, “There’s some guy out there asking questions about CoreWeave. Ignore him.” And that’s when I had my tinfoil hat made up because it’s the 2020s and the conspiracy theorists are winning this decade. I was like, “If you’re going to brand me a conspiracy theorist, I will wear that proudly because I’m the only one asking questions.” Now that was like $15 trillion of market cap ago, Dave. And maybe if we had asked these questions back in 2023, we wouldn’t have this hanging over everybody’s heads, but we didn’t. They told everybody don’t look, and now here we are.
David: Come on, Wall Street loves a good bubble. It’s a great way to make money. And who can argue against 15, 20 trillion in extra market cap? What you’re suggesting is, yeah, that’s fair, except that eventually there’s a bag holder and I care about my neighbor. I care about my mom and dad. I care about people who are unsuspecting investors who are positioned in a bag-holder trade.
And so yeah, okay, if we want to advance technology, if we want to revolutionize the way that we engage with productivity, all for it, let’s just not structure it in a way that’s so fragile that somebody who didn’t gain the benefits ends up paying the cost. And you said it earlier, we privatize, gain, socialize losses. That’s the modern way. And Wall Street doesn’t seem to object to it because they’re on the privatized gain side of the equation.
Jack: And buy-side research doesn’t sell, Dave. I mean, you turn on the press, it’s nothing but sell side. It’s all sponsored by this advisors and this fund and buy this ETF. That’s who is paying for the financial press. And so they’re not going to run a message that steers investors’ money away from the bubble that they’re selling. And so there’s just not very much market for it. There should be. People who are out there watching out for the average investor should be able to make money. You’d think that’d be a valuable service, but it doesn’t sell. You make a lot more money pumping alt coins or selling some highly levered ETF to South Korean investors than you would do in this.
David: All right. So how do our listeners keep up with you, Jack? What’s the best place for them to follow your work?
Jack: Best place would be on YouTube. I do a morning show every day, a morning update based on the news. I also do the occasional interview and investigative piece like the CoreWeave videos that I did. That’s Nobody Special is my channel on YouTube. I’m also Nobody Special Finance on Spotify and you can follow me on Twitter. I’m jg_nuke on Twitter.
David: JG_nuke.
Jack: Yes. From back in the nuclear days, that’s when I started my Twitter account.
David: Oh that’s fun. Well, thank you for joining us. It’s been really fun.
Jack: Thank you, Dave. I appreciate the opportunity.
* * *
Kevin: You’ve been listening to the McAlvany Weekly Commentary with our guest, Jack Gamble. You can find us at mcalvany.com and you can call us at 800-525-9556.
* * *
This has been the McAlvany Weekly Commentary. The views expressed should not be considered to be a solicitation or a recommendation for your investment portfolio. You should consult a professional financial advisor to assess your suitability for risk and investment. Join us again next week for a new edition of the McAlvany Weekly Commentary.